EN DE
Watch Tat Hong Equipment Service Co Ltd for free: we tell you when fair value or trend changes.
Data-driven stock valuation

Tat Hong Equipment Service Co Ltd (2153) fair value: what the stock is really worth

As of Nov 13, 2026: fair value (intrinsic value) of Tat Hong Equipment Service Co Ltd stock HK$0.69, price HK$0.83, that is 16.9% below the price, quality 39 out of 100. Rating: overvalued. Calculated from audited financials with 10 of our 26 valuation models and 37 quality factors, updated daily.

  1. Keep an eye on it?Free in your watchlist: 5 stocks without an account, 10 with one Yes, for free

Industrials HK · Based in China · ISIN KYG8683B1059

TH Tat Hong Equipment Service Co Ltd logo Thin data Nov 14, 2026

Tat Hong Equipment Service Co Ltd

2153 · HK

Expensive (fair value 17% below the price), weak company and falling price: meets none of the 3 rules.

Get notified free when this changes
Low debt 
Generates free cash flow 
Profit last quarter 34% below a year ago. 
Fair value HK$0.6900 · Overvalued 
Quality 39/100 
Falling price (downtrend) 
Weak Growth (revenue 5y −6.7 %/yr in HKD) 
Loss-making · -20.7% net margin (TTM) 
Trails peers (3/12) 
Narrow moat 9/100
Thin data 
Watch Tat Hong Equipment Service Co Ltd for free: we tell you when fair value or trend changes. Watch for free

What runs behind every stock

69 individual criteria per stock, every one traceable See the method →

Price vs Fair Value

HK$1.56 HK$0.7000 Fair Value HK$0.6900 Jul 2021 Nov 2026

White line = price, green steps = our fair value per fiscal year. As of Nov 14, 2026.

How to read this chart

60‑month range HK$0.7000 – HK$1.56 · fair‑value band HK$0.4700 – HK$1.05 · the HK$0.8300 price screens above the HK$0.6900 fair value. Green steps = our fair value per fiscal year (point-in-time, no hindsight). As of Nov 14, 2026.

Follow Tat Hong Equipment Service Co in your weekly email

Every Wednesday you see whether Tat Hong Equipment Service Co is on track or worth a review, plus price against fair value. Free, up to 3 stocks.

We send you a confirmation link. Unsubscribe with one click.

Which stocks are undervalued right now? Check free Discover now →

Company profile

Tat Hong Equipment Service Co., Ltd. provides tower crane solution services in the People's Republic of China.

Show moreShow less

The company offers consultation, technical design, commissioning, construction, and after-sales services to infrastructure, clean energy, traditional energy, public and factory building, and commercial and residential building.

It also engages in the installation, maintenance, leasing, and finance leasing of construction machinery and equipment. Additionally, it manages a fleet of tower cranes. The company was founded in 2007 and is headquartered in Shanghai, China.

Tat Hong Equipment Service Co., Ltd. operates as a subsidiary of Tat Hong Equipment (China) Pte. Ltd.

Stock analysis

Tat Hong Equipment Service Co Ltd (2153) currently trades at HK$0.8300, while our model-based Fair Value estimate is HK$0.6900, 17% below the price, so the stock looks overvalued today.

Show more

Valuation

Bull case: the Multiples group reads highest at a median of HK$1.56 per share, and 3 of the 10 models we run sit above the HK$0.8300 price.

Bear case: the Growth DCF group reads lowest at HK$0.5950, and 7 of the 10 models stay below the price. Data coverage for this calculation is low.

Scenario range: HK$0.4700 (bear) to HK$1.05 (bull), the price of HK$0.8300 sits inside it. Bear and bull are the same models on cautious and optimistic assumptions, a range, not a price target.

Quality & growth

The Quality Score stands at 39/100 (below-average quality), in the Industrials sector.

Weak Growth: Revenue is shrinking: the last year, the last three and the last five years are all negative.

Tat Hong Equipment Service Co Ltd reported revenue of 561M CNY in FY2026 versus 867M CNY in FY2022, a compound −10.3%/yr. Reported net income was −116M CNY in FY2026.

Key figures

Market cap HK$969M (≈ $123M) Micro · P/S ratio 1.67 · EPS (TTM) HK$−0.0500 · Net margin −20.7% · Return on equity −9.7% · Return on assets (EBIT) −0.4% (5-year average) · Operating margin −16.1% · Revenue (TTM) HK$582M.

Competitive moat

Our AI-assisted moat analysis scores the competitive advantage at 9 out of 100 (medium confidence).

What moves the price

The share trades about 22% below its 52-week high and 19% above its 52-week low, currently below its 200-day average.

For context, the median of 10 Industrials peers we cover trades at 10% fair-value upside, at −17%, 2153 screens richer than that median.

Fair Value models

Bear HK$0.4700 Fair Value HK$0.6900 Bull HK$1.05
Price HK$0.8300 · Downside -16.9%
Model ⓘEach model values the company its own way (discounted cash flow, earnings, assets, dividends). The fair value above starts from their evidence-weighted blend, not from a single model. In cyclical trough or peak years, after dilution or a stock split it is adjusted afterwards, so it can sit above or below the models. Bear ⓘBear = the cautious scenario: the same model computed with conservative anchors (lower growth, margins and valuation multiples). Together with Bull it frames a plausible valuation range, not a price target.BaseBull ⓘBull = the optimistic scenario: the same model computed with favourable anchors (higher growth, margins and valuation multiples). Together with Bear it frames a plausible valuation range, not a price target. If a model's bull case is above four times its base value, the table shows that limit with a > sign (like the overall Bull above): beyond it no assumption holds. Coverage ⓘCoverage = how well-backed THIS model's estimate is for this stock (0–100): how complete and reliable its input data are, and how well the model fits the company. The final Fair Value is an evidence-weighted blend, so better-evidenced models count more. Green ≥70, amber 50–69, grey below 50.
Best data coverage
FCF DCF HK$0.4500 HK$0.6800 HK$1.04 80
Growth DCF HK$0.4700 HK$0.6900 HK$1.01 78
Owner Earnings HK$0.3700 HK$0.5700 HK$0.9100 75
All 10 models by family
DCF Models
FCF DCF HK$0.4500 HK$0.6800 HK$1.04 80
Owner Earnings HK$0.3700 HK$0.5700 HK$0.9100 75
5Y Revenue Exit HK$0.2700 HK$0.4800 HK$0.7900 70
5Y EBITDA Exit HK$0.9500 HK$1.65 HK$2.59 74
10Y Revenue Exit HK$0.3400 HK$0.4900 HK$0.6400 67
10Y EBITDA Exit HK$0.7100 HK$1.13 HK$1.57 68
Multiples
EV/EBITDA HK$0.8900 HK$1.56 HK$2.23 65
Asset-Based
NCAV (Graham) HK$0.5900 HK$0.7900 HK$1.17 54
Growth DCF
Growth DCF HK$0.4700 HK$0.6900 HK$1.01 78
Rev-Margin DCF HK$0.2700 HK$0.5000 HK$0.8000 71

Open the full fair value analysis →

Quality Score breakdown

Overall quality 39/100

It rates the business: profits, how they develop, real cash, balance sheet, investing and share count.

Profitability 2
How much profit the company makes from its sales and capital
Quality Growth 32
Are margins and returns getting better?
Cashflow 50
Do the profits arrive as real cash?
Financial strength 32
Debt, balance sheet and risk of trouble
Investment 67
Does it invest with discipline instead of growing at any price?
Low Volatility 67
How calm the share price moves, does not count
Price momentum 30
Price momentum of the last 3 to 12 months, does not count
Near the 52-week high 23
Distance to the 52-week high, does not count
New shares 82
Buys back shares or issues new ones?

Open the full quality analysis →

Revenue & earnings trend

Growth Quality ⓘGrowth is valuable only when reinvestment earns attractive returns (Aswath Damodaran): sustainable growth depends on return on capital, reinvestment and efficiency. Basis: total company revenue over the periods shown on the cards (3Y/5Y/all years), not per share, so a merger can show up as a growth jump; per-share earnings growth is in the value-creation card. 17/100
Revenue is shrinking: the last year, the last three and the last five years are all negative.
Revenue growth 1 year
−11.5%
Revenue growth 3 years ⓘMeasures the company's TOTAL revenue from reported annual statements: compound average growth per year (CAGR) from the fiscal year 3, 5 or N years back to the most recent comparable fiscal year. Not per share: buybacks do not change this number, and a merger can appear as a growth jump. Per-share growth (which does include buybacks) is in the value-creation card.
−10.0%
Revenue growth 5 years ⓘMeasures the company's TOTAL revenue from reported annual statements: compound average growth per year (CAGR) from the fiscal year 3, 5 or N years back to the most recent comparable fiscal year. Not per share: buybacks do not change this number, and a merger can appear as a growth jump. Per-share growth (which does include buybacks) is in the value-creation card.
−6.7%
Start year 2021 (pandemic)
Revenue growth 8 years ⓘMeasures the company's TOTAL revenue from reported annual statements: compound average growth per year (CAGR) from the fiscal year 3, 5 or N years back to the most recent comparable fiscal year. Not per share: buybacks do not change this number, and a merger can appear as a growth jump. Per-share growth (which does include buybacks) is in the value-creation card.
+0.3%
Profit margin (trend) ⓘOperating margin then vs now, from reported annual statements. A falling margin after a boom year is the classic peak-earnings signal: the growth rate then leans on an inflated base.
18.8% (2021) → −13.8% (2026)
What shareholders gained per year ⓘWe only publish this rate when it is defensible. Reason: fiscal 2026 is a loss year, no rate is defined from a loss
not computed

Growth Forecast

A lot of optimism in the price
The price assumes more growth than the company has delivered so far.
What the price assumes ⓘThis turns our valuation around: instead of asking what the share is worth, it asks what growth the current price requires. It uses the cash the company keeps after all spending (free cash flow), the same discount rate as our models, five years of growth, then slowing evenly to 2 % a year by year ten. Compared with the analysts' sales forecasts extended to the same five years (at least three analysts, for context only, it does not enter the Fair Value): within 3 percentage points counts as "in line" (amber), below that little optimism (green), above that a lot of optimism (red).
+23.0%
Yearly growth needed for the next five years to justify today's price.
What forecasts expect
n/a
No analyst forecast available.
After inflation (figures in CNY, China: IMF forecast 1.7% a year to 2030, 1.4% from 2016 to 2025) that is about +21.0% a year for the price.

2153 screens overvalued: fair value 17% below the price. Compare with Caterpillar Inc →

Compare Tat Hong Equipment Service Co Ltd with another stock

Price, fair value, quality and upside side by side.

Free, no sign-up

Peer GroupⓘHow this stock ranks against its industry: the green marker is this stock, the band is the typical 25–75% peer range, and the tick is the median.Farm & Heavy Construction Machinery · 152 stocks

Beats the industry median on 3/11 measures
Overall it trails its industry peers.
Valuation
Quality Score 39 · Bottom 25%
Fair Value upside −16.9% · Below median
Profitability
Return on assets −4.1% · Bottom 25%
Net margin (12 months) −20.7% · Bottom 25%
Operating margin (12 months) −16.1% · Bottom 25%
Growth and dividend
Revenue growth (quarter YoY) −4.5% · Bottom 25%
Balance sheet
Debt / equity 0.42× · Highest 25%

Valuation Multiplesvs Farm & Heavy Construction Machinery median · lower = cheaper

P/B 0.82× · Cheapest 25%
P/S (12 months) 1.67× · Pricier than median
Price / free cash flow (fiscal year) 17.2× · Cheaper than median
EV/EBITDA 8.7× · Cheaper than median

Strength profile in five axes (Snowflake)

VALUEFUTUREPASTHEALTHDIVIDEND
This stock
VALUEFUTUREPASTHEALTHDIVIDEND
Sector peers
VALUE (fair-value potential)11 · sector 39
FUTURE (revenue growth)0 · sector 45
PAST (return on equity)0 · sector 35
HEALTH (low debt)79 · sector 94
DIVIDEND (yield)0 · sector 39

Context: sector, industry, market

Values & ESG

Does this company touch areas you may want to avoid? The classification is inferred from sector and industry.

None of the checked exposures detected

Similar stocks

10 more Farm & Heavy Construction Machinery stocks, each showing price versus our Fair Value estimate.

Stock Price Fair Value vs Fair Value Compare
Sinotruk (Hong Kong) Limited 3808 HK$33.94 HK$57.08 +68% vs 2153
XCMG Construction Machinery Co 000425 ¥6.46 ¥9.74 +51% vs 2153
Daimler Truck Holding DTG €42.66 €49.89 +17% vs 2153
Sany Heavy Industry Co 600031 ¥18.32 ¥20.84 +14% vs 2153
PACCAR Inc PCAR $106.66 $117.33 +10% vs 2153
Metso Oyj METSO €17.12 €18.83 +10% vs 2153
Traton SE 8TRA €34.34 €35.62 +4% vs 2153
CNH Industrial N.V CNH $11.91 $8.67 −27% vs 2153
Caterpillar Inc CAT $600.20 $283.68 −53% vs 2153
Deere & Company DE $673.54 $260.32 −61% vs 2153

Explore undervalued stocks

More undervalued Industrials stocks →

Try a ready-made strategy

Pick a strategy and jump into the live analysis with that exact screen applied.

🥇 Backtested Best 🏆 Big Names 💎 Quality on Sale 🚀 Profitable Growth 🧊 Quality Compounders 💵 Dividend Stars 📈 Strong Momentum 📉 Fallen Angels ⚖️ Deeply Undervalued 🔍 Small-Cap Gems 🏰 Moat at a Fair Price 💼 Insider Buying 🎩 Buffett-Style Quality 📚 Peter Lynch GARP 🧮 Greenblatt Magic Formula 🛡️ Graham Defensive

Discover tools

For bloggers & editors: embed code + live data

For bloggers, editors and developers: paste this into your site or blog (a “Custom HTML” block in WordPress), it shows the current fair value and links back here. Free, plain HTML, and welcome. Full data streams (CSV/JSON) at /developers.
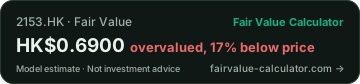
Tat Hong Equipment Service Co Ltd: fair value per Fair Value Calculator

Cite: Fair Value Calculator (2026). "Tat Hong Equipment Service Co Ltd Fair Value". https://www.fairvalue-calculator.com/stock/2153

Frequently asked questions

Is Tat Hong Equipment Service Co Ltd (2153) overvalued or undervalued?
As of Nov 14, 2026, our model estimates a fair value of HK$0.6900 versus a price of HK$0.8300, about 17% lower (overvalued).
What is the fair value of 2153?
Our model-based fair value for Tat Hong Equipment Service Co Ltd is HK$0.6900 (as of Nov 14, 2026), built from audited fundamentals. The current price: HK$0.8300.
What is the quality score of 2153?
Tat Hong Equipment Service Co Ltd has a Quality Score of 39/100. It measures business quality (profitability, growth, cash flow, balance-sheet strength, investment discipline, share issuance). Market factors such as price momentum and volatility do not enter the number; they are shown separately in the detail view.
What is the price target for Tat Hong Equipment Service Co Ltd (2153)?
Our model-based price target is the fair value of HK$0.6900 (as of Nov 14, 2026) from 10 valuation models. Cautious scenario HK$0.4700, optimistic scenario HK$1.05. It is a calculation from audited fundamentals, not an analyst target.
What is the Tat Hong Equipment Service Co Ltd stock forecast for 2026?
Our models put fair value at HK$0.6900, about 17% lower versus a price of HK$0.8300 (overvalued). Cautious scenario HK$0.4700, optimistic scenario HK$1.05. The calculation is refreshed regularly with new filings.
What is the revenue of Tat Hong Equipment Service Co Ltd (2153)?
Tat Hong Equipment Service Co Ltd reported trailing-twelve-month revenue of about HK$582M (latest available figure, as of Nov 14, 2026).
What growth is priced into Tat Hong Equipment Service Co Ltd (2153)?
For today's price to be fair in a discounted-cash-flow model, Tat Hong Equipment Service Co Ltd would have to grow free cash flow by 23.0 % per year for five years (discount rate 11.8 %, then slowing evenly to 2 % perpetual growth by year ten). Over the last 5 years revenue fell 6.7 % per year. As of Nov 14, 2026.
What discount rate (WACC) does the fair value of 2153 use?
Our models discount Tat Hong Equipment Service Co Ltd at 11.8 %: a base by market capitalisation (micro), damped by beta 0.39, country premium for Hong Kong. The same rate applies in all 26 models.
What is a reverse DCF?
A reverse DCF turns the usual calculation around. Instead of deriving a value from assumptions, it takes today's price as given and asks: what free-cash-flow growth would a company have to deliver for exactly this price to be fair? The result is not a forecast but the expectation already priced in. For Tat Hong Equipment Service Co Ltd that is +23.0 % per year for five years, then slowing evenly to 2 % by year ten, using the same discount rate (11.8 %) and the same formula as our fair value.
How much growth has Tat Hong Equipment Service Co Ltd (2153) delivered so far?
Over the past 5 years revenue at Tat Hong Equipment Service Co Ltd shrank 6.7 % a year. The price currently implies free-cash-flow growth of +23.0 % per year. Comparing the two shows how much confidence is in the price: if it demands more than has been delivered, the business has to accelerate for the maths to work.
How fast is the sector of Tat Hong Equipment Service Co Ltd (2153) growing?
The median revenue growth in the sector is +7.9 % a year. That is the yardstick for the growth priced into Tat Hong Equipment Service Co Ltd (+23.0 % per year): it shows whether the expectation is within the usual range or beyond it.
What is the free cash flow yield of Tat Hong Equipment Service Co Ltd (2153)?
The free-cash-flow yield on the price is 6.82 %: that much free cash flow Tat Hong Equipment Service Co Ltd produces per unit of market value. When it exceeds the discount rate of our models (11.8 %), the business already earns more than its cost of capital demands, and the price needs little additional growth.
What is the intrinsic value of Tat Hong Equipment Service Co Ltd (2153)?
Intrinsic value and fair value mean the same thing: what the business is worth on its numbers, independent of the share price. For Tat Hong Equipment Service Co Ltd it is HK$0.6900 per share (as of Nov 14, 2026), against a price of HK$0.8300. It is the blended result of 10 valuation models in 4 families (DCF Models, Multiples, Asset-Based, Growth DCF).
Is Tat Hong Equipment Service Co Ltd stock overvalued or undervalued in 2026?
As of Nov 14, 2026, 2153 trades above its calculated fair value: price HK$0.8300, fair value HK$0.6900, a gap of about −17% (overvalued). The calculation is refreshed with each new quarterly report, so the verdict can change during the year.
Is fair value the same as the market price of 2153?
No. The price is what the market pays today (HK$0.8300); the fair value is what the company's own numbers justify (HK$0.6900). For Tat Hong Equipment Service Co Ltd the two are HK$0.1400 per share apart. That gap is exactly why we show both numbers side by side.
How much is Tat Hong Equipment Service Co Ltd worth?
The market values Tat Hong Equipment Service Co Ltd at about HK$969M (market capitalisation, as of Nov 14, 2026). Per share that is HK$0.8300; our models calculate a fair value of HK$0.6900 per share.
What do the bullish and bearish scenarios say about 2153?
Our models span a range for Tat Hong Equipment Service Co Ltd: cautious scenario HK$0.4700, base HK$0.6900, optimistic HK$1.05 per share (as of Nov 14, 2026, price HK$0.8300). The range comes from different growth and margin assumptions, not from analyst opinions.
How solid is the balance sheet of Tat Hong Equipment Service Co Ltd (2153)?
Balance-sheet figures for Tat Hong Equipment Service Co Ltd (as of Nov 14, 2026): return on equity −9.7%, debt of 0.42 per unit of equity. They feed the Quality Score of 39/100, which measures business quality independently of the share price.
How far is 2153 from its 52-week high?
Tat Hong Equipment Service Co Ltd trades at HK$0.8300, about 22% below its 52-week high of HK$1.07 and 19% above the low of HK$0.7000 (as of Nov 13, 2026). Distance from the high says nothing about value: that is what the fair value of HK$0.6900 is for.
Which stocks are comparable to Tat Hong Equipment Service Co Ltd?
From the same area (Industrials) we also value Caterpillar Inc, Deere & Company, PACCAR Inc, Daimler Truck Holding, among others. Each of them has its own fair-value calculation on this site using the same models, so the comparison is like for like.
Is Tat Hong Equipment Service Co Ltd stock attractive at the current price?
The data as of Nov 14, 2026: price HK$0.8300, calculated fair value HK$0.6900 (−17%), Quality Score 39/100, from 10 models. Whether that fits your horizon and risk tolerance is your call. We provide the calculation, not investment advice.
How is the fair value of 2153 calculated?
We run Tat Hong Equipment Service Co Ltd through 10 models from 4 families: DCF Models, Multiples, Asset-Based, Growth DCF. Every model gets the same audited fundamentals; the fair value of HK$0.6900 builds on their evidence-weighted average, with the spread shown as a cautious and an optimistic scenario.
Is it still worth investing in stocks now?
The global stock market currently sits 14.5% above its aggregate fair value. Tat Hong Equipment Service Co Ltd itself currently trades above fair value. An expensive market is no reason to stay out and no reason to buy everything at once: keep a broad savings plan running, buy single stocks only with money you can do without, and hold part of your money liquid while the market is high. The full picture including sectors is on is it worth investing now.
What is the share price of Tat Hong Equipment Service Co Ltd (2153)?
The closing price on Nov 13, 2026 was HK$0.8300. Our model-based fair value is HK$0.6900, about 17% lower (overvalued). We carry closing prices from our data provider, not a live tick.
What should I pay attention to with Tat Hong Equipment Service Co Ltd right now?
Weak quality (39/100) and above fair value at the same time, the margin of safety is missing on both counts. A fairly wide model range (HK$0.4700 to HK$1.05) leaves room in how you read the outcome. Evidence is limited here (fewer models, shorter history), so the fair value is a rougher estimate than usual.

Key figures of Tat Hong Equipment Service Co Ltd

How large is the market capitalisation of Tat Hong Equipment Service Co Ltd (2153)?
The market capitalisation of Tat Hong Equipment Service Co Ltd is HK$969M (≈ $123M). The stock-market value of the whole company: share price times number of shares. It is what the market asks for the entire business today.
What is the P/S ratio of Tat Hong Equipment Service Co Ltd (2153)?
The price-to-sales ratio of Tat Hong Equipment Service Co Ltd is 1.67 (last twelve months). Price to sales: market value relative to yearly revenue. Useful when profit is thin or distorted.
What are the earnings per share of Tat Hong Equipment Service Co Ltd (2153)?
Earnings per share at Tat Hong Equipment Service Co Ltd are HK$−0.0500. Earnings per share over the last twelve months: total profit spread across every single share.
What is the net margin of Tat Hong Equipment Service Co Ltd (2153)?
The net margin of Tat Hong Equipment Service Co Ltd is −20.7% (fiscal year 2026). How much of every unit of revenue ends up as profit. 10% means 10 cents of profit per dollar of sales.
What is the return on equity of Tat Hong Equipment Service Co Ltd (2153)?
The return on equity (ROE) of Tat Hong Equipment Service Co Ltd is −9.7% (last twelve months). Profit relative to shareholders' equity, how efficiently the company works with its owners' money.
What is the EBIT return on assets of Tat Hong Equipment Service Co Ltd (2153)?
On an EBIT basis the return on assets of Tat Hong Equipment Service Co Ltd is −0.4% (avg 5y). Operating profit (EBIT) relative to everything the company owns, as a multi-year average. It describes the business model rather than one good or bad year.
What is the operating margin of Tat Hong Equipment Service Co Ltd (2153)?
The operating margin of Tat Hong Equipment Service Co Ltd is −16.1% (last twelve months). Profit from the core business (before interest and taxes) relative to revenue.
How fast is revenue growing at Tat Hong Equipment Service Co Ltd (2153)?
Revenue at Tat Hong Equipment Service Co Ltd is down 4.5% versus a year earlier (3y avg −10.0%). How much revenue grew versus a year earlier (YoY). The 3-year average next to it puts the single year in context.
How fast are earnings growing at Tat Hong Equipment Service Co Ltd (2153)?
Earnings per share at Tat Hong Equipment Service Co Ltd are down 33.7% versus a year earlier. How much earnings per share grew versus a year earlier.
How much net debt does Tat Hong Equipment Service Co Ltd (2153) carry?
The net debt of Tat Hong Equipment Service Co Ltd is HK$1.1B (fiscal year 2026, ≈ 19.8 yrs of FCF). Debt minus cash on hand. The note shows how many years of free cash flow could in theory pay it off.
Free · no account needed

Watch Tat Hong Equipment Service Co Ltd in the live analysis

One click puts Tat Hong Equipment Service Co Ltd on your watchlist: fair value and trend at a glance, plus comparison, the diversification check and the 27,000+ stock screener.

Watch for free →

Zero risk: nothing is ever charged. Your watchlist is yours, with or without an account.